Why Your Salary Disappears Before the End of the Month
Month start ayina ventane mekku salary ostadhi kani , Month end avvuku mundhey me salary ayipotadhi.
Chala mandhi ki idhey problem,main ga problem enti ante vala entha earn chestharu ani adhi monthly expenses kavachu ledha regular payments ledha small spendings ayi undachu.
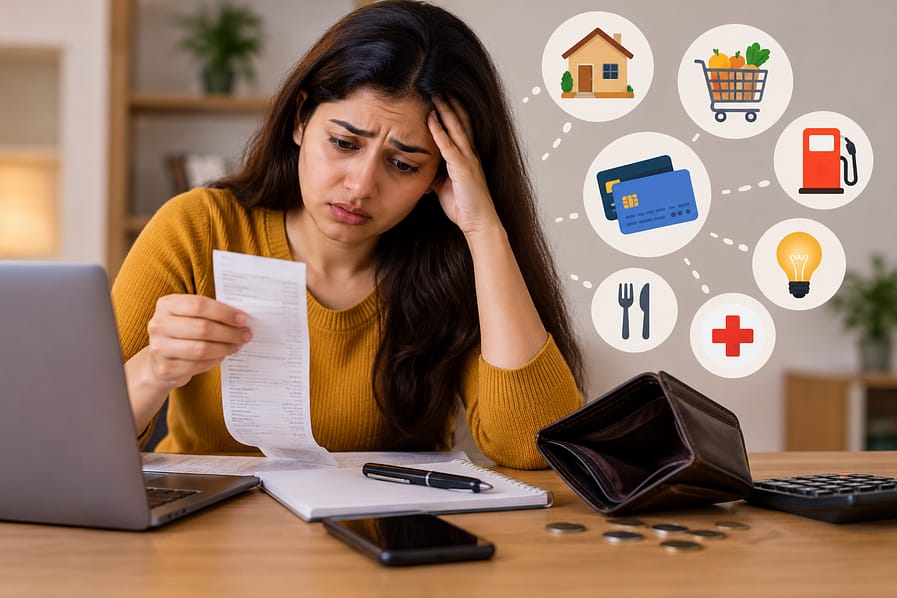
Prathi Month salary endhuku ante essential expenses, savings, and personal needs. chala mandhi chala ibbandhi padtharu salary tesukunaka aa salary ni malla ink salary tesukney varuku unchukovdham.Rent, food, transport, electricity bills, loan payments, and daily purchases veti vala mana bank account lo unna paisal ayipothuu untai.
Why Your Salary Disappears Before the End of the Month
Is Essential Expenses Take Up a Large Part of Your Salary
Housing, food, electricity, transport, healthcare, and other basic needs often account for a large share of monthly income.
People living in cities face higher rent and commuting costs. Families may also need to pay school fees, support Family or older relatives, or manage medical expenses.
When essential expenses consume most of the salary, there is little room left for saving or unexpected cost.
The first step is to calculate the total cost of essential expenses. It helps show how much money remains for other needs after the main bills are paid.
Loan EMI’s and Credit Card Payments Reduce Available Income
Loans and credit card balances can place pressure on a monthly budgets.
A home loan, personal loan, vehicle loan, or other borrowing may require fixed paymets every month. These payments reduce the amount available for groceries, transport, savings, and other expenses.
Credit cards can make spending feel less immediate because the money does not leave the bank account at the time of purchase. However, the bill must be paid later.
credit card balance are not full paid in full, interest and applicable charge may increase the total amount owed. People who repeatedly use credit to cover basic expenses may find it increasingly difficult to manage their next salary.
loan payments, credit card bills, interest rates, and repayment dates can identify financial pressure before it becomes harder to manage.
Online Shopping and Food Delivery Increase Spending
Online shopping and food delivery services make everyday purchases convenient. They can also make it easier to spend money without planning a head.
Discounts, limited-time offers, free delivery conditions, and recommendations can people to buy items they did not originally intend to purchase.
A low er price does not alwa ys mean a saving if the purcha se was unnecessary.
One practical ap proach i s to wait 24 hours b efore buying non-esse ntial items. This gives buyers time t o decide whether they gen uinely need the prod uct.
Setting a sepa rate monthly limit f or shopp ing and food delivery can als o help prev ent these expe nses from affecting money re serv ed f or bills and sa vings.
Un expected Expenses Disturb the Monthly Budget
Not every expense can be predicted.
Medical treatment, vehicle repa irs, urgent travel, house mainte nance, and fa mily can create costs that were not included in the original budget.
Without emergency savings, people may need to use credit cards, take out loans, or reduce spending on other important needs.
An emergency fund can help these costs without disrupting the entire month’s budget. The amount required depends on income stability, household responsibilities, existing debt, and access to other financial support.
Building this fund gradually can provide greater financial flexibility over time.
There Is No Clear Monthly Spending Plan
A person can know their salary amou nt without knowing exactly where that money goes.
Without a spending plan, it is easy to underes timate the c ost of regular purc hases or forget bills that are due later in the month.
Basic monthly budget :
-
Take-home salary after deductions.
-
Essential household expenses.
-
Loan and credit card payments.
-
Savings and emergency funds.
-
Personal spending and optional purchases.
Once these categories are recorded, the remaining balance becomes easier to understand.
A budget is not meant to prevent every enjoyable purchase. Its purpose is to help people spend within their means while making room for important financial goals.
How to Make Your Salary Last Until the Next Payday
A few practical changes can make monthly income easier to manage.
Track spending for 30 days. Record purchases, bills, online payments, and cash expenses. Use bank statements or a simple spreadsheet to identify where the money goes.
Plan for fixed bills first. Set aside the amounts needed for rent, utilities, loan payments, and other essential commitments.
Divide variable expenses into weekly limits. Instead of treating the entire monthly balance as available money, assign limits to groceries, trans port, and personal spending.
Save an affordable amount regular ly. Start with an a mount that does n ot interfe re with essential needs. Increase it when your financial situation allows.
Review subscri ptions and recurring p ayments. Canc el services that are n o longer useful and check for charges you may have overl ooked.
Avoid unnecessary bo rrowing. Using credit to co ver rou tine spending can mak e future month s mo re dif ficult, particularly when interest and fees apply.
Review your budget before the next pa yday. Com pare planne d spen ding with ac tual spending an d adjus t the following month’s plan.
 A Simple Monthly Salary Budget Example
 A Simple Monthly Salary Budget Example
The following example shows how a person earning ₹30,000
Monthly Salary Budget Example
Example budget for a monthly take-home salary of ₹30,000.
| Expense Category | Monthly Amount |
|---|---|
| Rent and household bills | ₹10,000 |
| Groceries and food | ₹6,000 |
| Transport and mobile expenses | ₹3,000 |
| Loan payments and other commitments | ₹4,000 |
| Savings and emergency fund | ₹3,000 |
| Personal spending and unexpected costs | ₹4,000 |
| Total Monthly Salary | ₹30,000 |
Note: This is an illustrative budget. Actual expenses vary depending on income, location, family size, and financial commitments.
This example assumes that the listed expenses cover the person’s main financial needs. Actual costs may be much higher or lower depending on location, family size, existing debt, and individual circumstances.
The main lesson is to assign a purpose to each part of the salary rather than treating the entire balance as money available for unrestricted spending.
Common Reasons Your Salary Runs Out Early
Understanding Why Salary Disappears Before the End of the Month
Understand common spending problems and practical ways to manage your monthly salary.
| Common Problem | Effect on Monthly Finances | Practical Solution |
|---|---|---|
| High essential expenses | Leaves little money for other needs | Review fixed costs and essential spending |
| Frequent small purchases | Reduces the balance gradually | Track daily expenses |
| Loan and credit card payments | Limits money available for living costs | Review repayments and borrowing costs |
| Unplanned online shopping | Uses money reserved for other purposes | Set a spending limit |
| No emergency savings | Makes unexpected bills harder to manage | Build a small emergency fund over time |
Note: These are common examples. Actual financial challenges vary according to income, household expenses, debt, and personal circumstances.
Google Drive Folder 1
Google Drive Folder 2
CONCLUSION
A salary that disappears before the end of the month can be the result of several factors, including high household expenses, loan payments, frequent small purchases, unexpected bills, and a lack of clear financial planning.
Tracking expenses, planning for essential payments, setting realistic spending limits, and saving an affordable amount regularly can help people gain better control over their money. These steps may not solve every financial problem, especially when income is too low to cover basic needs, but they can make spending patterns clearer.
Going forward, the most useful approach is to review the monthly budget regularly and make changes based on actual expenses rather than estimates. With a clearer understanding of income and spending, individuals can make more informed decisions about saving, borrowing, and preparing for future costs.